
By Jérémie Feuillette, Managing Director, Global Head of ILO
Gian Giacomo Della Torre and I have published a paper arguing that much of what banks treat as an intraday liquidity shortage is liquidity trapped between payment rails.
Liquidity on the wrong rail: a network view of intraday liquidity examines a cost the Federal Reserve first identified in 2006 and that conventional treasury systems do not measure: banks paying counterparties on one payment rail and being paid back another.
For a top-10 global bank, on both CHIPS and Fedwire, we estimate the mismatch costs $4M–$7M a year in direct funding cost, and $10M–$21M once intraday liquidity buffers are included.
The full paper sets out the cost model, the worked examples, and the stablecoin analysis behind each one.
Read the full paper: Liquidity on the wrong rail: a network view of intraday liquidity
What is a CHIPS–Fedwire rail mismatch?
In June 2006, the Federal Reserve named “mismatches of payments sent over CHIPS and Fedwire whereby some participants are consistently long (or short) for the CHIPS settlement” as one of four root causes of late-day Fedwire congestion (Consultation Paper on Intraday Liquidity Management and Payment System Risk Policy, 21 June 2006).
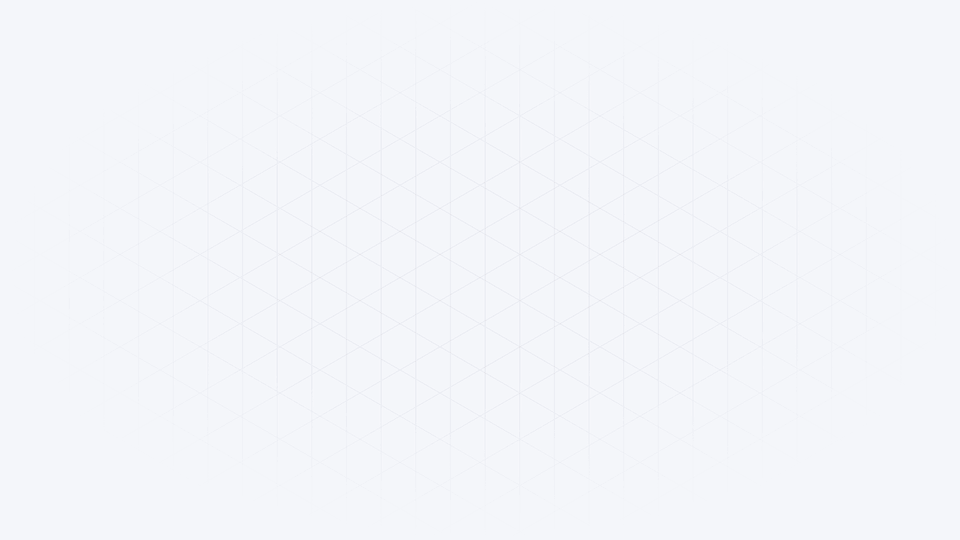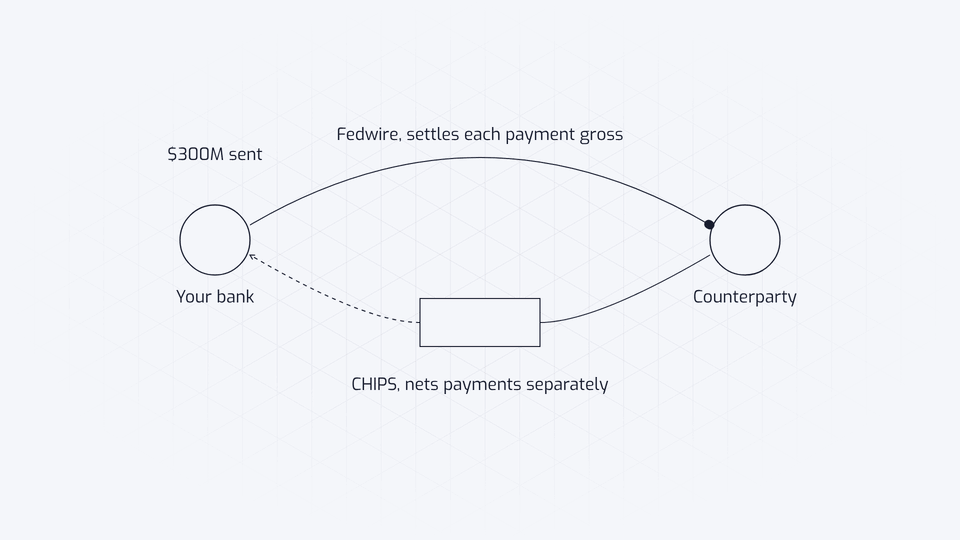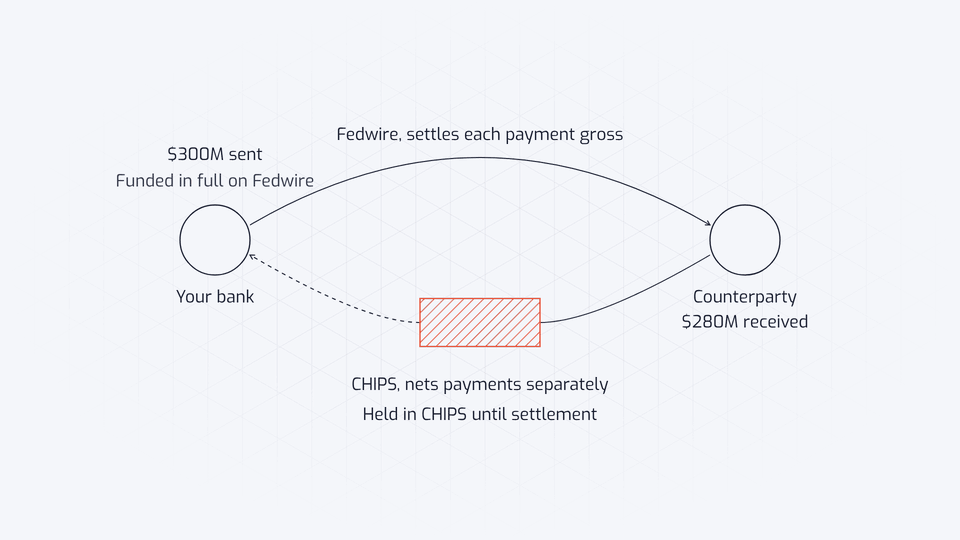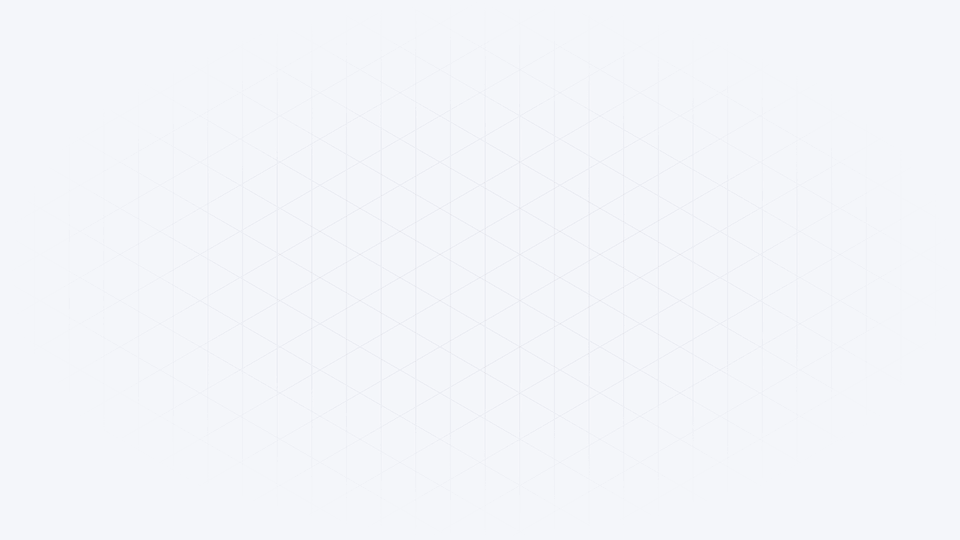
The paper explains why the problem has persisted for 20 years: no conventional treasury management system measures payments per counterparty and per rail at the same time. Consider a bank that sends $300M to a counterparty on Fedwire and receives $280M back on CHIPS. Gross flows nearly balance, so the firm-level recycling ratio looks healthy. Fedwire settles each payment gross, however, and CHIPS nets separately, so the two flows never offset. The bank has funded the full $300M on Fedwire, while the $280M it receives back stays inside CHIPS until settlement.
How to measure intraday liquidity trapped between payment rails
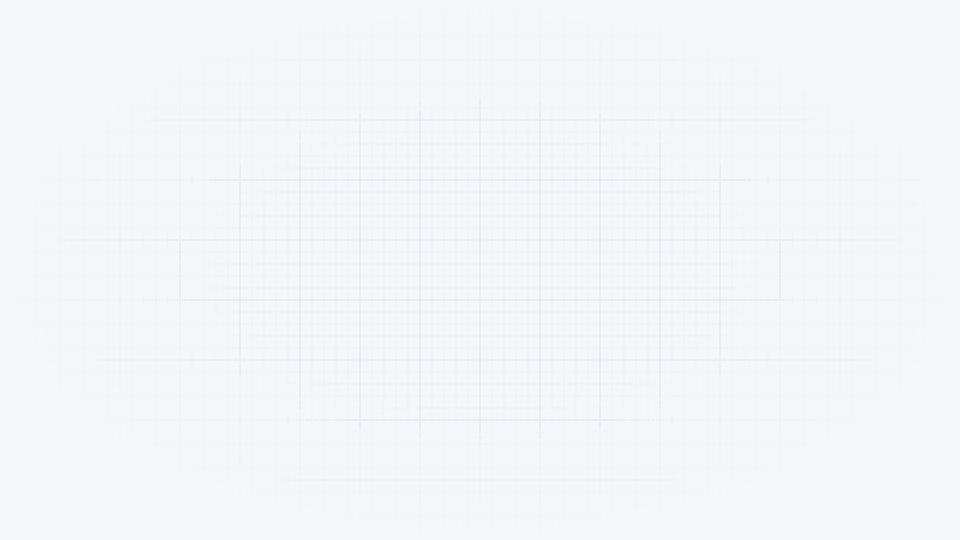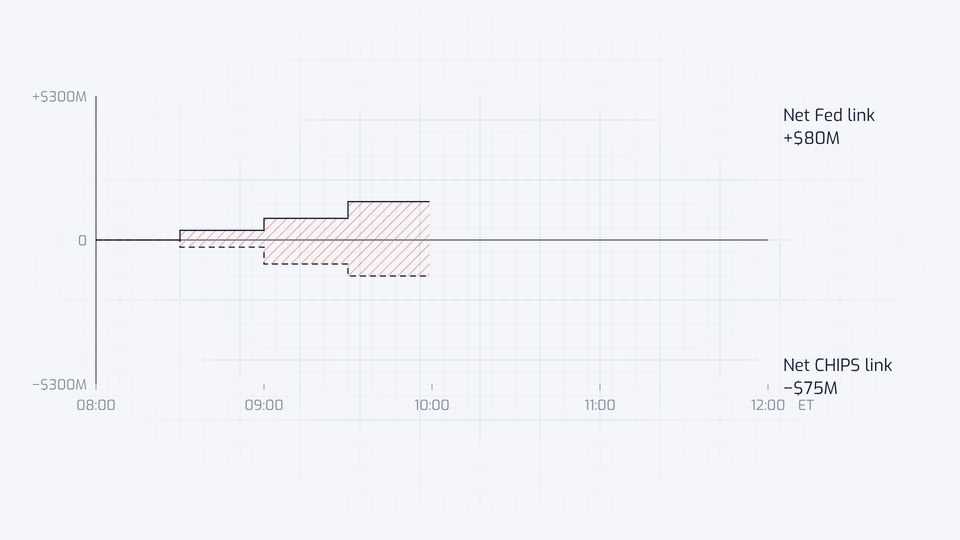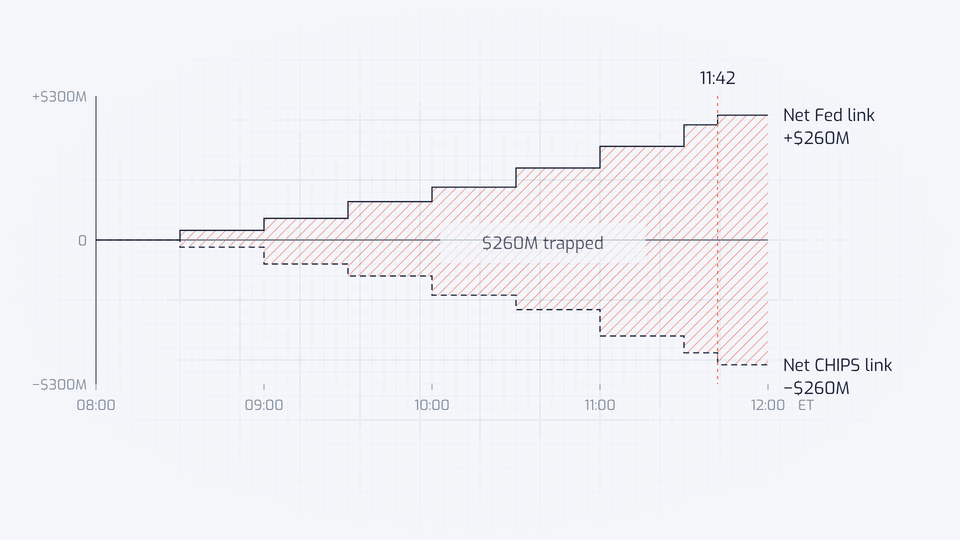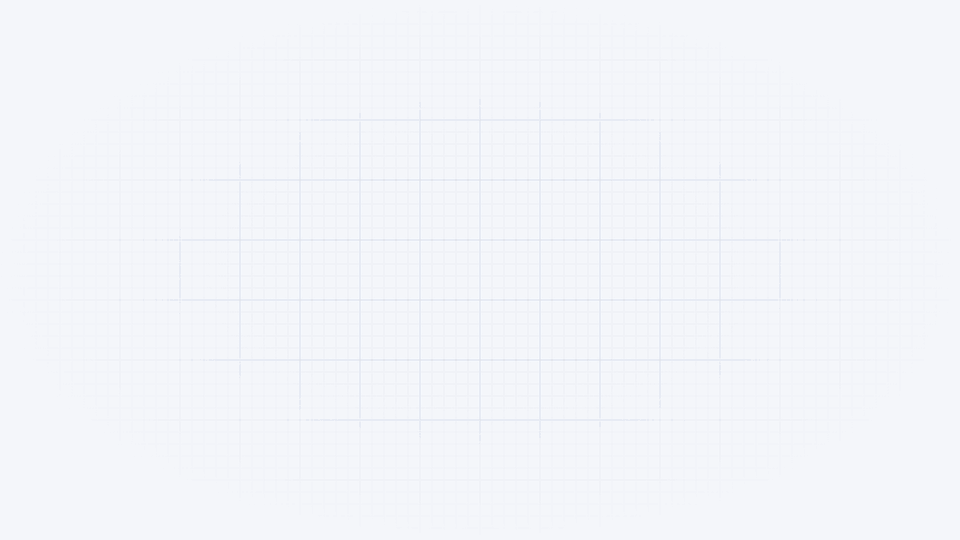
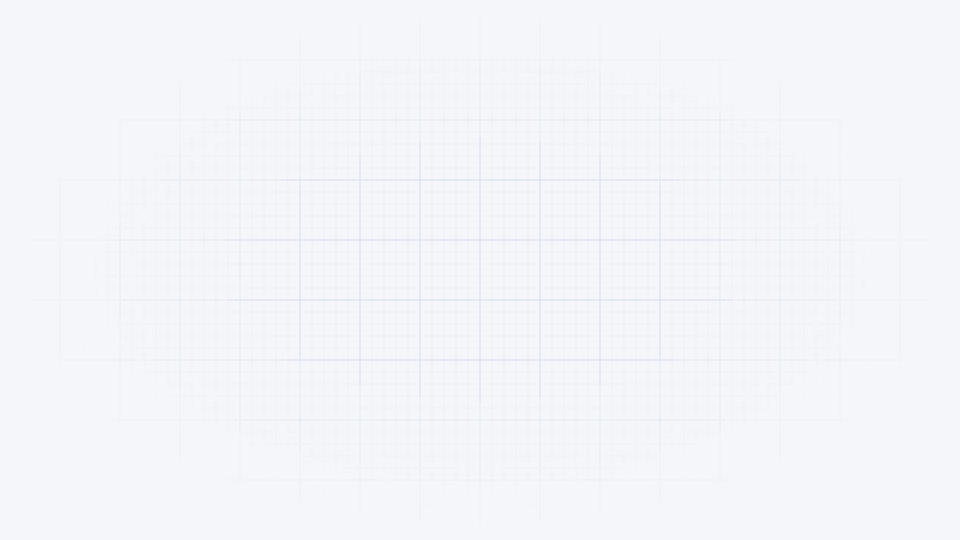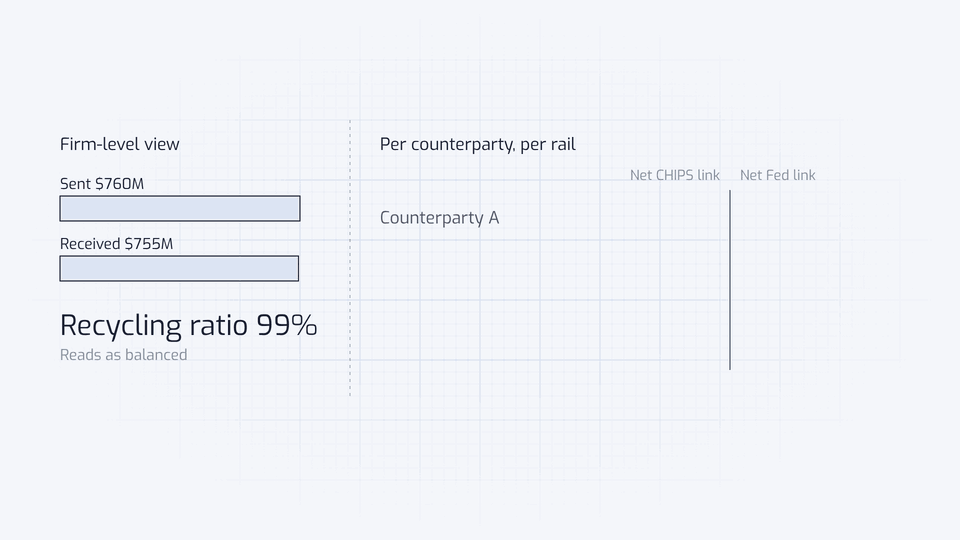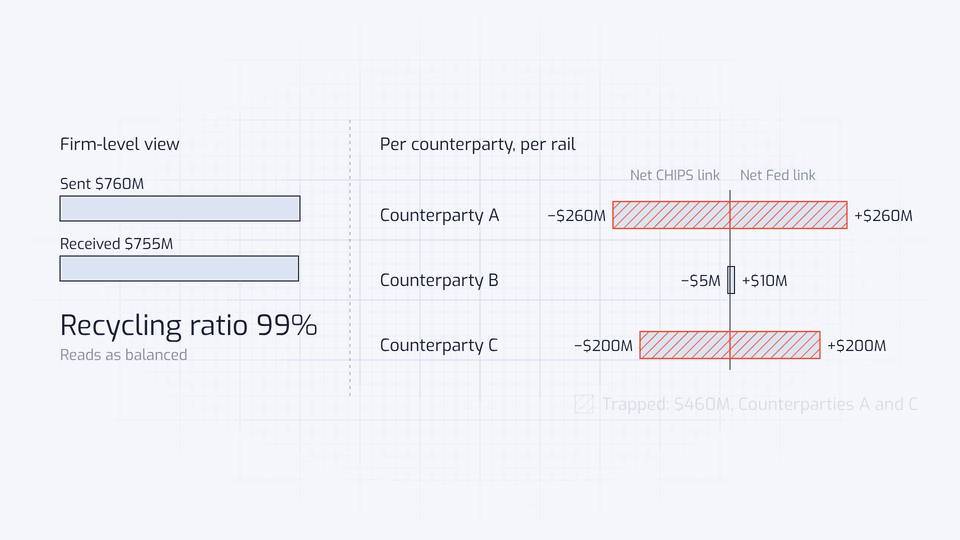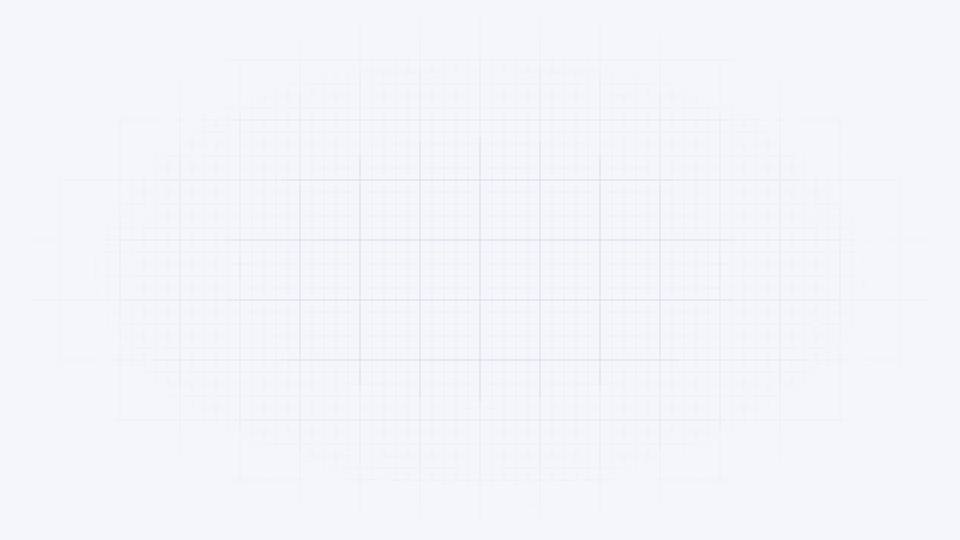
At the core of the paper is a simple measure: two net links per counterparty, computed in real time. Net Fed Link is Fedwire out minus Fedwire in, and Net CHIPS Link is the same for CHIPS. When the two are equal and opposite, for example +$260M and −$260M, the counterparty is a rail mismatch and $260M is trapped. The figure is read directly from the data and does not depend on a model.
The paper then sets out a three-tier decision rule for treasury teams: reroute, queue, or draw credit. It also works through a three-counterparty example in which a 99% recycling ratio hides $460M of trapped liquidity. The measure works because the paper treats liquidity as a flow across a network of counterparties and rails rather than a balance on a ledger, the approach set out in Network Theory and Financial Risk by FNA’s Samantha Cook and Kimmo Soramäki.
Why the recycling ratio misses trapped intraday liquidity
Across the Intelligent Liquidity Optimisation (ILO) engagements I have been part of over the past 18 months, every bank we analysed showed rail mismatch above 20% of gross bilateral flow volume on its top-five CHIPS–Fedwire counterparties. In almost every case, the firm-level recycling ratio was within the bank’s own tolerance.
On that basis, the paper suggests the recycling ratio remains useful for reporting and oversight, while the bilateral net link is better suited to intraday liquidity management decisions. The paper sets out the profit and loss case in three parts: direct funding cost, buffer release, and avoided regulatory remediation. It also explains why deployment takes four to six weeks rather than the 18 months often estimated for integration. The paper also maps supervisory direction, from the Prudential Regulation Authority’s (PRA) CP5/26 to the European Central Bank’s (ECB) Sound Practices, toward more granular, rail-specific intraday measurement.
Rail symmetry: liquidity optimisation for multi-rail payments
The second half of the paper looks ahead. The same mismatch is appearing between fiat and digital money, on a rail growing about 45% a year. Stablecoin transactions reached $33 trillion in 2025, up 72%, and the GENIUS Act brought payment stablecoins inside a US federal framework in July 2025.
Corporate treasuries are starting to use these rails. On 30 October 2026, Bloomberg reported that Uber had used HSBC tokenised deposits to hold a Franklin Templeton tokenised money market fund from Thursday to Sunday, earning about 1.5 extra days of yield. The paper explains how the party funding a Sunday redemption carries the same equal-and-opposite position, held open across the weekend.
For a bank with a material stablecoin on/off ramp business, we estimate fiat–stablecoin mismatch at $5M–$15M a year today, rising to $15M–$45M by 2028–2029. The paper proposes treating stablecoins as a denomination rather than an asset class, which brings stablecoin liquidity management into the same framework as fiat. It also introduces rail symmetry, a single framework for multi-rail payments covering Fedwire, CHIPS, CHAPS, T2, FedNow, USDC, tokenised deposits, and wholesale central bank digital currency (CBDC). Our view, set out in the conclusion, is that by 2028 the bilateral rail-matched net link will be the standard unit of intraday liquidity measurement.
How can you test your bank for rail mismatch?
The paper closes with four claims a Group Treasurer or US Treasurer can check against their own data within a month. One check takes a single query: split payment data by counterparty and by rail, then compare net Fedwire and net CHIPS positions for your top 20 counterparties. Where the two are close to equal and opposite, liquidity is trapped between the rails. The paper sets out the other three checks and the evidence behind each.
Read the full paper: Liquidity on the wrong rail: a network view of intraday liquidity
To discuss the findings, contact Jérémie Feuillette at jeremie.feuillette@fna.fi. We can run the assessment on a sample of your payment data in two weeks, followed by a full proof of concept (POC) that sizes the mismatch across your counterparty book.
Frequently asked questions
What is the paper Liquidity on the wrong rail about?
Liquidity on the wrong rail is an FNA paper by Jérémie Feuillette and Gian Giacomo Della Torre on bilateral rail mismatch in intraday liquidity. The paper covers the CHIPS–Fedwire mismatch the Federal Reserve identified in 2006, a net link diagnostic for measuring it, and the profit and loss case for addressing it. It also extends the framework to stablecoin and tokenised deposit rails.
What is a CHIPS–Fedwire rail mismatch?
A CHIPS–Fedwire rail mismatch is a counterparty relationship where a bank pays out on one rail and is paid back on the other. Fedwire settles each payment gross, while CHIPS nets payments, so a $300M Fedwire outflow cannot be offset by a $280M CHIPS inflow from the same counterparty. The value stays trapped until late in the day.
Why does the recycling ratio miss trapped intraday liquidity?
The recycling ratio adds up inflows and outflows across every counterparty and every rail, so a large Fedwire position and an equal, opposite CHIPS position cancel out in the total. In the paper’s three-counterparty example, a 99% recycling ratio hides $460M of trapped liquidity. Intraday liquidity optimization software measures the mismatch per counterparty in real time.
Does rail mismatch apply to stablecoins and tokenised deposits?
Yes. A bank minting stablecoins against fiat pays out on a fiat rail and receives on-chain, the same pattern as Fedwire against CHIPS. Because on-chain rails run 24/7, the exposure window can stretch to 72 hours across a weekend.
